
Why Hazard Insurance Matters When You’re Buying a Home

Published on Apr 15, 2025 | Purchasing a Home
Why Hazard Insurance Matters When You’re Buying a Home

As you approach the finish line in your homebuying journey, you may come across something called hazard insurance in your closing documents. If you’re wondering what it is and why it’s required—don’t worry, you’re not alone.

Let’s break it down in simple terms.

What Is Hazard Insurance?

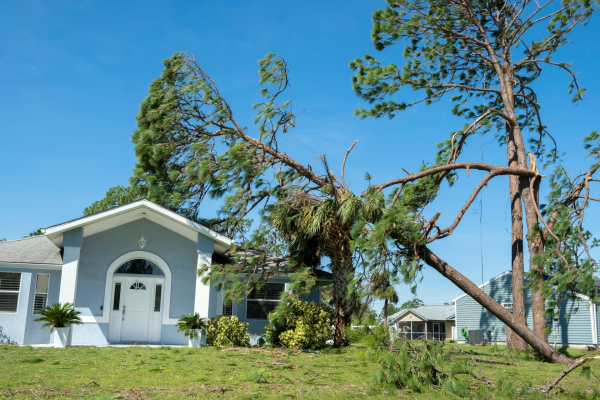
Hazard insurance, often included as part of your homeowners insurance policy, protects your property from damage caused by specific risks. These “hazards” typically include:

  • Fire
  • Wind or hail storms
  • Lightning or smoke
  • Theft or vandalism
  • Explosions
  • Some types of water or ice damage

If your home is damaged by a covered event, hazard insurance helps cover the repair or replacement costs.

Why You Need Hazard Insurance

If you’re using a mortgage to buy your home, your lender will require hazard insurance before closing. Until you fully repay your loan, the property acts as collateral. Lenders want to protect that investment in case disaster strikes.

Even if you’re buying the home in cash, going without insurance puts your finances at serious risk. One unexpected event could wipe out years of savings.

The One-Year Rule

Most lenders require you to prepay the first year of hazard insurance at closing. This cost will be part of your “prepaid items” listed in your loan estimate and closing disclosure.

It’s a required upfront expense, but it ensures your home is protected from day one—and that your loan can close on time.

How to Choose the Right Policy

Take time to compare quotes from at least three to five insurance companies. You’ll want to review:

  • Monthly premium
  • Covered hazards
  • Deductible amount
  • Policy limits

Keep in mind, standard hazard insurance doesn’t cover things like floods, earthquakes, or sewer backups. Depending on your location, you may need extra coverage for those risks.

Also, choosing a higher deductible can lower your monthly premium—but make sure you can afford that deductible in case you ever need to file a claim.

Can You Write Off Hazard Insurance?

In most cases, hazard insurance premiums aren’t tax-deductible unless the property is used for rental or business purposes. However, they can sometimes be included in itemized deductions for second homes or investment properties. Ask your tax advisor for specific guidance.

The Bottom Line

Hazard insurance isn’t just a requirement—it’s an important safety net for your home and finances.

Here’s what to remember:

  • It protects your home from specific risks like fire, storms, and theft.
  • Lenders require you to have a policy in place before closing.
  • You’ll likely need to prepay the first year at closing.
  • Shop around to find the right balance of cost and coverage.

Need help finding the right hazard insurance before closing?
Contact us today—we’ll guide you through the process and help you stay on track for a smooth home purchase.

Recent Posts

Blog Tags

Purchasing a Home Reliant Mortgage VA Loans Refinancing a Home Atlanta Homebuyers Reliant Mortgage Home Loans Atlanta Homebuyers First-Time Homebuyer Atlanta Buyers Interest Rates Reliant Mortgage Mortgage Preapproval First-Time Homebuyer Reliant Mortgage FHA Reliant Mortgage Decatur Homebuyers Credit Atlanta Homebuyers Atlanta Homeownership Mortgage Lenders Reliant Mortgage Conventional Mortgage Atlanta Mortgages Lithonia Homebuyers Homebuying Checklist Mortgage Underwriting Tucker Buyers Down Payment Assistance Atlanta Mortgages Lithonia Homebuyers Loan Comparison Mortgage Escrow Mortgage Underwriting Student Loans First-Time Homebuyer Decatur Homebuyers Car Payment Down Payment Assistance Atlanta Investors Compare Mortgage Lenders Homebuyer Negotiation Mortgage Preapproval Earnest Money Atlanta Real Estate Atlanta Homebuyers Home Insurance Georgia Dream Down Payment Assistance Debt-to-Income Ratio Gift Funds Atlanta Renters Property Taxes Reverse Mortgage Atlanta Homebuyers Debt-to-Income Home Loan Documents Homeownership Costs Home Appraisal Atlanta Duplex Atlanta Homebuyers DSCR Closing Cost Atlanta Renters Lawrenceville Homebuyers Affordability Atlanta Homebuyers Georgia Dream Mortgage Qualification Down Payment Mortgage Qualification Atlanta Homebuyers Owner Occupied Duplex Georgia Closing Costs Rental Property Financing Mortgage Rate Lock Home Loan Rates Homebuying Timeline New Construction Buy Before Selling Mortgage Credit First-Time Buyers Georgia Homebuyers Mortgage Documentation Copy tags Homebuying Timeline Atlanta Condo Buyers Jumbo Mortgage First-Time Homebuyer Lawrenceville Homebuyers Self Employed Mortgage Down Payment Assistance Cash to Close Rental Income Escrow Conyers Homebuyers Mortgage Escrows Atlanta Relocation Stone Mountain Buyers Mortgage Payments Bridge Financing Georgia Homebuyers Tucker Homebuyers Mortgage Refinance Decatur Homebuyers Atlanta Relocation Condo Mortgage Solo Homebuyers Bonus Income Decatur Homebuyers New Construction Prepaid Expenses USDA Property Taxes Mortgage Preapproval Credit Freeze Closing Costs Atlanta Homebuyers Home Loan Qualification Self-Employed Mortgage Georgia Homeowners Seller Credits moving to Atlanta HOA, Property Overtime Pay 1099 Income Assistance Repayment Decatur Homebuyers Builder Incentives VA Benefits PMI Removal Moving to Georgia Decatur Buyers Georgia Homebuyers Self-Employed Borrowers Business Income Closing Costs Moving to Georgia HOA Conyers Homebuyers Atlanta Business Owners Atlanta Homebuyers Atlanta New Construction Credits Tucker Homeowners PMI Conditional Approval New Debt Seller Credits Atlanta Homebuyers Non-QM Loans Mortgage Documents Tucker Homebuyers Conditional Approval Lithonia Homebuyers Atlanta Condos Bank Statements New Car Gift Funds Self-Employed Borrowers Loan Estimates Georgia Closing Costs Homebuying Timeline, Condo Mortgage Payments, Reliant Mortgage,